
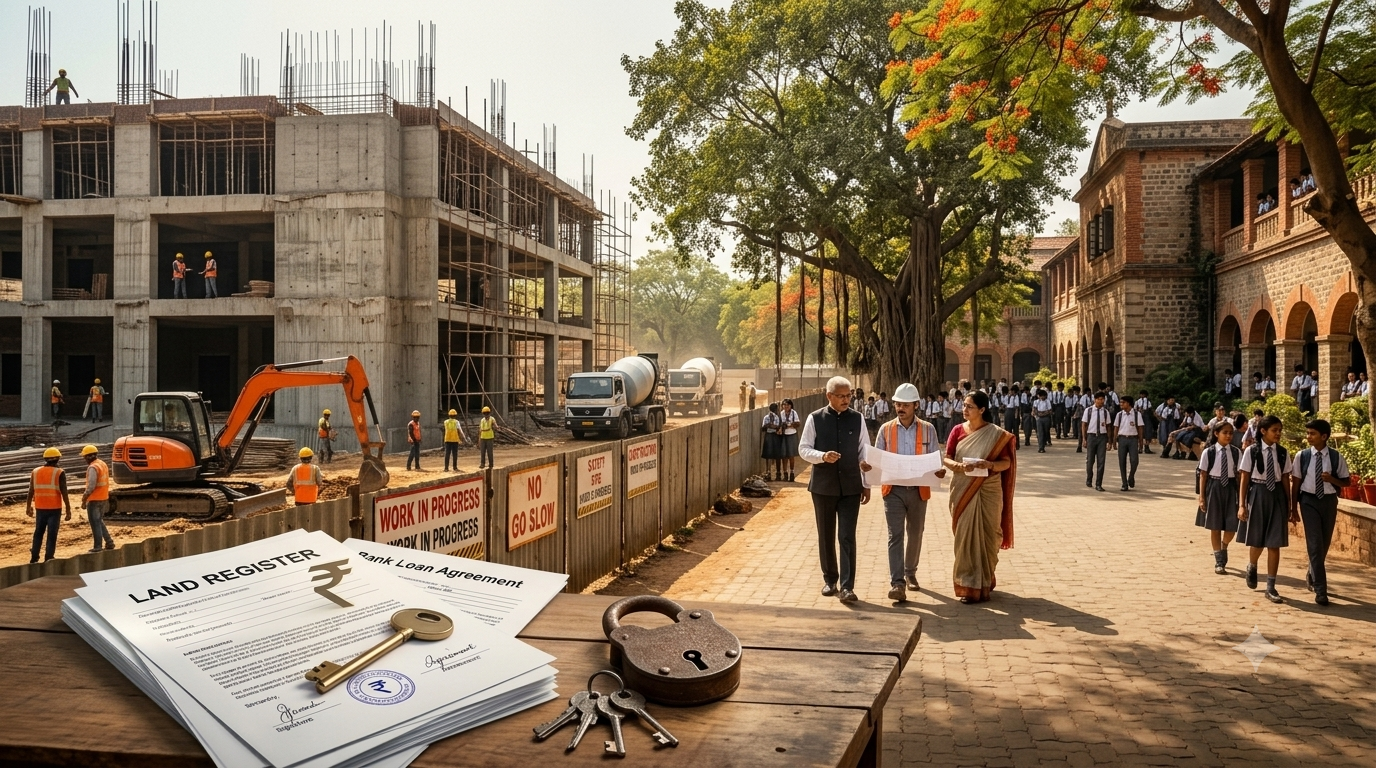
For private schools experiencing steady growth, expanding infrastructure is often essential to accommodate more students, introduce new facilities and support long-term development. A school construction loan can help school owners fund these projects without putting excessive pressure on their existing finances. Lenders offer both secured and unsecured financing options, depending on the borrower’s eligibility and requirements. However, when applying for a secured loan, providing collateral is an important part of the lending process.
If you are a school owner or leader planning to finance a construction project, read on to understand the basics of school construction loans, particularly collateral for school construction loans.
Is a School Construction Loan Worth It?
The answer is yes. If your school has a healthy financial record and has been delivering quality education, don’t let procrastination get in the way of its growth. A school construction loan can help you strengthen your institution’s infrastructure while keeping its finances on track. Here’s what it can help you achieve:
- Preserve working capital: Ensures funds are available for salaries, utilities, supplies and routine operating expenses.
- Upgrade existing facilities: Renovate aging buildings, improve sanitation and address essential repairs.
- Expand classrooms: Accommodate growing student enrollment to prevent overcrowding.
- Modernize learning spaces: Set up or upgrade science labs, computer rooms, smart classes and libraries.
- Improve student amenities: Develop sports facilities, multipurpose halls and other shared spaces.
- Increase campus capacity: Add floors or buildings to accommodate future growth.
Secured Loan vs. Unsecured Loan
Before applying for a school construction loan, it is important to understand how secured and unsecured loans differ, along with the advantages and limitations of each. This will help you choose a financing option that best suits your school’s financial position and construction plans.
What is a secured loan?
A secured loan for school construction is a type of financing in which the borrower pledges an asset as collateral to secure the loan.
What is an unsecured loan?
An unsecured loan does not require the borrower to pledge an asset as security. Instead, lenders assess the borrower’s creditworthiness, financial health and repayment capacity before approving the loan.
|
Advantages of a Secured Loan |
Disadvantages of a Secured Loan |
|
Higher loan amounts: Subject to the value of the collateral and repayment capacity. |
Asset at risk: Failure to repay can result in the lender recovering the asset. |
|
Longer repayment tenure: Can offer more time to repay, helping manage monthly installments better. |
Documentation requirements: Property ownership and other collateral-related documents are required for school construction loan |
|
Competitive interest rates: Interest rates may be lower than unsecured loans. |
Longer approval process: Asset verification and legal checks may increase loan processing time. |
|
Greater borrowing flexibility: Can support substantial construction and infrastructure projects. |
– |
| Advantages of an Unsecured Loan | Disadvantages of an Unsecured Loan |
|---|---|
|
No collateral needed: You can access financing without pledging property or other assets. |
Lower loan amounts: Borrowing limits may be lower than those of secured loans. |
|
Faster processing: The absence of collateral assessment can simplify and speed up the approval process. |
Higher interest rates: Lenders may charge more to compensate for the absence of collateral. |
|
Lower financial risk to assets: Your pledged asset is not at stake because no collateral is offered. |
Stricter credit assessment: Approval depends on financial health, credit history and repayment capacity. |
| Useful for smaller projects: Can help fund limited construction or renovation needs. | – |
Collateral for School Construction Loan: What You May Need to Pledge
If you consider a secured loan as the more suitable financing option for your school’s construction needs, the next step is to understand what you may need to offer as collateral. This will help you prepare for the application process and make an informed borrowing decision.
When evaluating the collateral requirements for school loans, remember that the collateral for a school construction loan may depend on the lender’s policies and the nature of the financing.
Here are some common forms of collateral that lenders in India may accept for a secured loan for school construction:
- School land and building: The property on which the proposed construction will take place may be mortgaged to the lender. This is a common form of security for institutional construction loans.
- Other immovable properties: Lenders may accept residential or commercial properties owned by the school trust, society, or other eligible borrowers. A property mortgage for a school loan may also involve an existing property owned by the promoters, subject to lender approval.
- Assets acquired through the loan: Machinery, equipment, and other assets purchased using the loan may be hypothecated to the lender as primary security.
Additionally, some lenders may require guarantees from key promoters, trustees, or office-bearers as additional repayment assurance. These are separate from physical collateral.
Keep in mind that lenders may carry out legal checks, including property valuation and title verification, before accepting an asset as security. They may also require the property to be free from existing encumbrances.
A Financing Partner That Understands Your School’s Needs
Choosing a school-focused lender like Varthana can make a meaningful difference to your financing experience.
Unlike legacy and corporate banks that cater to borrowers across multiple sectors, Varthana, an RBI-registered school finance company, focuses specifically on financing private schools. We understand the distinct challenges school owners face and accordingly offer financing solutions.
Guided by a mission to transform affordable education in India by financially empowering private schools, Varthana is not merely a lending institution. We collaborate with school leaders, providing holistic academic and management support to strengthen the institution and improve student outcomes. Having partnered with over 13,500 schools across 15 states, we have positively impacted the educational journey of more than 6.5 million students.
This school-focused approach makes Varthana a compelling financing partner for institutions planning their next phase of growth, via an unsecured or secured loan for school construction.
Here are some key features that make Varthana a strong choice when considering a secured loan for school construction:
- Secured financing for larger projects: Schools can obtain secured loans of up to ₹10 crore, with repayment tenures of up to 15 years.
- Multiple collateral options: Varthana provides a wide range of collateral options for secured school loans, subject to its specific assessment and lending policies.
- Flexible EMI options: Repayment schedules can be structured around your school’s cash flow and repayment capacity.
- Fast processing: Loans are processed within 5–7 working days after submission of the required documents.
- Dedicated Relationship Manager: Avail the services of a Relationship Manager who works as an on-ground partner providing personalized, hands-on assistance throughout the process, from application to disbursement.
Thus, with our specialized understanding of private schools, customized financing, academic and management support, and hands-on assistance, we offer more than conventional lending. We bring financial resources and education-focused expertise together to help schools move forward.
Have plans to build, expand, or upgrade your school? Give those plans the financial support they deserve. Get in touch with Varthana today to explore your options for a secured loan for school construction.
FAQs
-
What can be used as collateral for a school construction loan?
Varthana offers multiple collateral options for secured school loans, subject to its lending policies. Usually, the collateral for a school construction loan may include school property or other eligible immovable assets. -
Can I mortgage my existing property to secure a school loan?
Yes. Varthana could accept a property mortgage for school loan, subject to property valuation and ownership verification. -
Can I get a school construction loan without collateral?
Yes, private schools that meet our school loan eligibility criteria can access unsecured loans of up to ₹40 lakh without pledging collateral. -
What are the school loan eligibility criteria for a secured loan from Varthana?
The applicant must be an Indian citizen aged 26–70 years. The school must be run by a promoter, association, or trust, have operated for at least three years and have a minimum enrollment of 200 students. Required documents include KYC proofs, school registration, 12-month bank statements, financial records, a completed application form and collateral documents such as property ownership papers, title deeds and relevant property records.

Social