
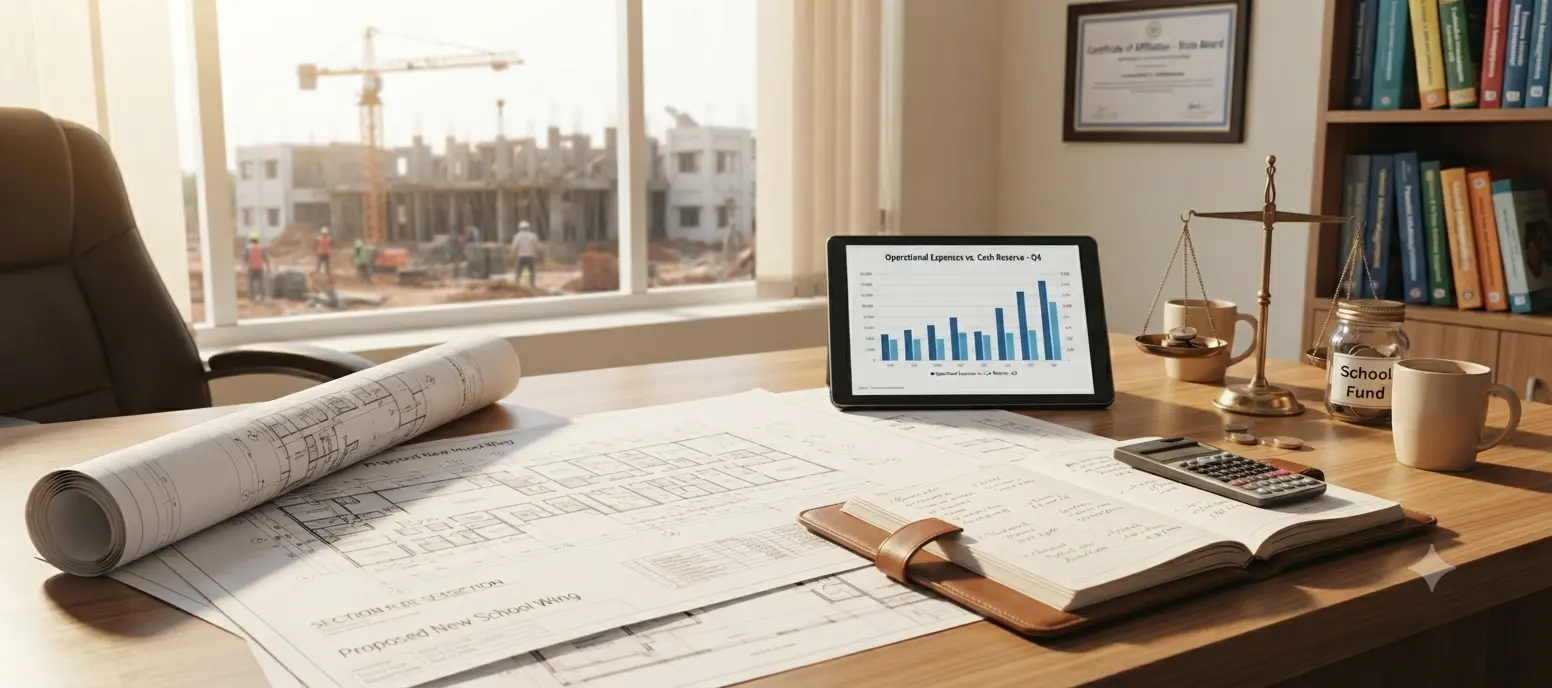
School owners planning a construction or expansion project must decide whether to pay for it using the school’s available cash reserve or by taking out a loan. Paying in cash helps avoid additional debt, but it also reduces the funds that would otherwise go toward the school’s fixed monthly expenses, such as salaries, rent, and loan payments. If fee collections slow down after that cash is spent, the school may not have enough reserves to cover these essential payments.
To avoid this, school owners must determine how much cash to set aside before committing any funds to a construction or expansion project. Determining the right amount is the purpose of school cash reserve planning. This blog explains the two types of reserves a school may maintain, how to build these reserves, and when borrowing may be the better choice.
Why Your School Needs a Cash Reserve
School fees are collected at specific times during the academic year, while fixed expenses, such as salaries, rent, and maintenance, must be paid monthly. Managing these two timelines is key to cash flow management for schools. The mismatch typically occurs in these three situations:
- At the start of a new academic session, when schools must pay staff salaries and maintain the premises before the first fee collections come in.
- During the summer break, when schools have to cover staff salaries and other expenses even when fee collections are slower than expected.
- Whenever parents delay fee payments because the school’s expenses remain unchanged while fee collections fall below the amount due.
A construction project draws on the same cash reserves that schools rely on to manage these periods. Therefore, you first need to fix the reserve, then fund the project with whatever remains or through a loan.
Two Types of Cash Reserves a School May Maintain
Your school may maintain two types of cash reserves, which differ in how their amounts are determined and how the funds may be used.
- Mandatory reserve: A type of fund your school must set aside and maintain under government regulations or education board requirements. It serves as a financial safety net, ensuring money is available when needed to meet legal requirements. Its use is restricted, so you cannot spend it on routine operating expenses. According to the CBSE’s Affiliation Bye-Laws, schools must maintain a reserve fund when required by the state government. The required amount, calculation method, and permitted uses vary from state to state.
- Operating reserve: This is your school emergency fund, the money set aside to cover expenses during months when fee collections fall short. The amount is not set by law; instead, your school determines it based on its operating expenses.
How Much Operating Reserve to Keep
Your operating reserve is measured against your monthly school operating expenses, such as salaries and benefits, rent and building maintenance, existing loan installments (EMIs), and statutory obligations, such as provident fund contributions. One-time purchases and discretionary expenses are excluded, as they are not part of the school’s monthly operating costs.
Operating reserve = Monthly operating expenses × Months of cover
To decide how many months your operating reserve should cover, review your fee collection records month by month. Find the longest period in which the fee collections fall short of operating expenses. The length of this period will help determine how many months of expenses your reserve must cover. Maintaining this record is one of the most practical school cash flow management strategies.
Next, adjust the reserve based on your fee collection schedule. If parents pay fees annually or once per term, add an extra month’s worth to cover expenses at the beginning of the next academic session before new fee collections begin. If some parents delay fee payments, add the fees that are usually collected late or remain unpaid. Basing the reserve on actual fee collection records rather than on a general rule is a sound approach to financial planning for private schools.
How to Build Your Operating Reserve
If your balance is below the target, keep the reserve in a separate bank account so that the daily expenses do not deplete it. Set aside a fixed share of every fee collection, recover unpaid fees, and postpone discretionary spending until the reserve reaches its target.
When to Borrow Instead of Using Your Reserve
Consider borrowing when all three conditions are met:
- Your operating reserve already meets your target number of months of expenses.
- Using the reserve to fund the project would bring the balance below the target level.
- The income generated by the project, such as fees from newly enrolled students, can cover the monthly installment along with your existing expenses.
Use your school emergency fund to cover gaps in fee collections and borrow to finance construction and equipment purchases. If you spend the reserve on construction and fee collections are delayed, you may struggle to pay salaries, rent, and existing loan installments. You may have to delay payments or arrange emergency funds mid-project.
If your school’s cash reserve is below its target, build it up first, as taking a loan will add another monthly expense.
Benefits of Borrowing Instead of Depleting Reserve
- Day-to-day funds stay safe: Your operating reserve remains available to cover regular expenses throughout the project.
- More students, more fee income: New classrooms or laboratories enable you to accommodate new students and generate more fee income.
- Smaller payments over time: You repay the loan in monthly installments over the agreed tenure instead of paying the full cost upfront.
- An earlier start: You can begin construction once the loan is approved rather than waiting to save the full amount.
How the Right Financial Partner Can Support Your School
Varthana is an RBI-registered, education-focused non-banking financial company (NBFC) that has disbursed school loans to over 13,500 schools across 15 states, supporting more than 6.5 million students. We offer flexible repayment schedules, so you can align installments with your school’s cash flow and keep your operating reserve intact. We assign a dedicated relationship manager and process school loans within 5–7 working days after receiving the required documents.
At Varthana, we offer two types of loans:
Secured loans (collateral required)
- Suited to large-scale construction or expansion projects
- Up to ₹10 crore, with a repayment period of up to 15 years
- The school should have operated for at least three years and have 200 or more students
Unsecured loans (no collateral required)
- Suited to smaller construction or renovation projects
- Up to ₹40 lakh
- The school should have operated from owner-owned premises for at least five years, with 400 or more students
Both loan options are available to Indian applicants aged 26 to 70 who manage schools run by a promoter, association, or trust.
At Varthana, we help schools find suitable financing for their growth plans. Get in touch with us, and we’ll help you explore the right loan option for your school.
FAQs
-
Does taking a loan change how much operating reserve I need?
Yes. A loan adds to your school’s monthly financial commitments. When calculating your school operating expenses, include the monthly loan installment. Use this revised monthly amount to calculate how much your operating reserve should cover. -
How do we calculate our cash reserve target?
Your cash reserve target is the minimum amount you should have saved before borrowing. Cash reserve target = monthly fixed costs × 3 to 6 months Monthly fixed costs include salaries, rent or loan EMIs, utilities and maintenance. -
How often should I review my operating reserve?
Review your operating reserve at least once a year and whenever your monthly expenses change, such as when you take a new loan or revise staff salaries.


Social